Data analytics for credit unions and banks who mean business

A world-class data analytics solution where growth is encouraged and opportunities are made obvious

Drive decisions through strategic insights and tangible action

Individual profitability

Financial Analytics

Al Queries

Data Quality & Governance

Data Quality & Governance

Customer Insights

General Ledger Visibility

Gemineye partners with the brightest banks and credit unions across the country

veridian
us community
university
third federal
sunmark
sscu
space coast
peak
nusenda
numark
logix
leaders
gesa
dfcu
credit union 1
Communitywide
CapEd
cape and coast
4front
Suncoast CU
Quorum
P1FCU

What makes the Gemineye Data Lakehouse different?

slinky icon

Scalability

Our scalable design means there are no limits on what data can be brought in, both now…and as you grow.

tetris icon

Integrations

Our flexible infrastructure plays well with virtually every integration, even the ones that are notoriously tricky.

Stopwatch illustration in mint green.

Implementations

Our implementations take months, not years to be fully operable, so you can benefit from your data journey early.

Built for modern financial institutions

At Gemineye, we believe that a modern data program should be both practical and usable. Our best-in-class data warehousing and contextual AI solutions lower the barrier to creating a data-driven culture and make success in analytics finally accessible. 

Whether you are a $300M credit union or a $30B bank, every community financial institution should have access to a data solution that works the way you need it to. We’re Gemineye – allowing you to drive the data and the journey. Hop in.

Illustration of a helicopter putting down a piece of a building with a sign on it that says Hello Financial.

Hear from Our Clients

When we went through our vendor selection process, and spoke with other credit union leaders, Gemineye was a clear winner for us. Their speed of implementation, pre-built solutions for our critical software platforms, native cloud and Databricks architecture, out-of-the-box data visualization solution, extremely high praise from existing clients, and very competitive pricing model made them a winner for CU1.
Marvin Anunciacion – Homepage
Marvin Anunciacion
Director of Data Analytics
Credit Union 1
$1.5B Assets
Purple quote icon
Purple quote icon
Showing Slide 1 of 2

The Gemineye Data Lakehouse, built for efficiency

The Gemineye Lakehouse is a single, cloud-native platform that leverages the best elements of a data warehouse and a data lake, saving you time and money in big ways. 

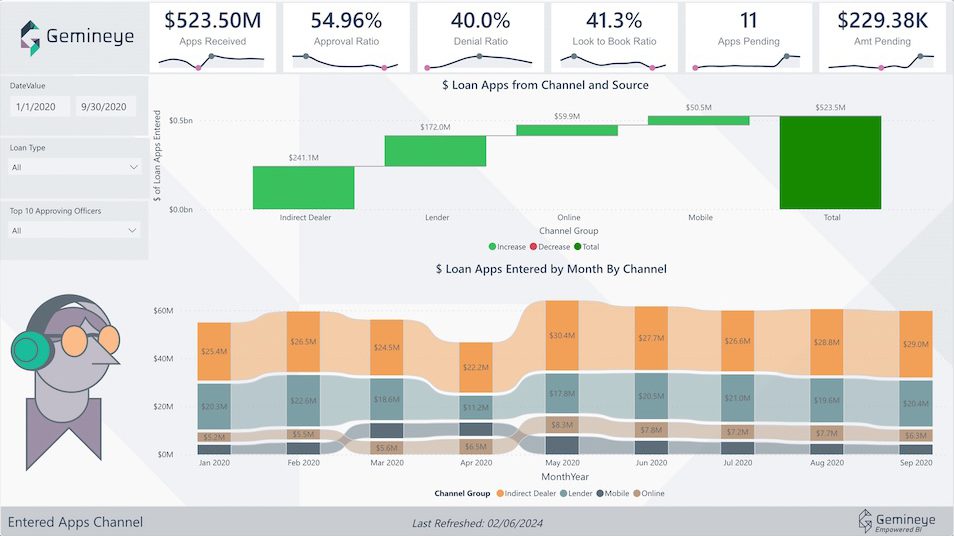
Gemineye Data Lakehouse entered apps channel screenshot
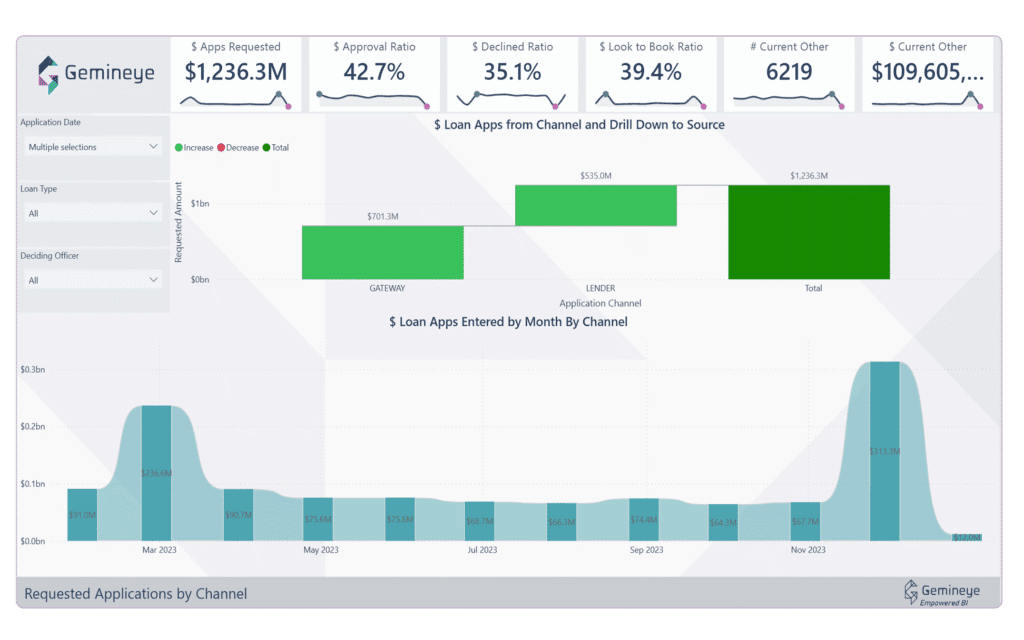
The Gemineye Data Lakehouse Applications by Channel
Illustration of a can of sardines

For those sick of being a sardine

Break free of the tiny, dark can with a data analytics partner who adapts to your financial institution’s specific needs, not the other way around. 

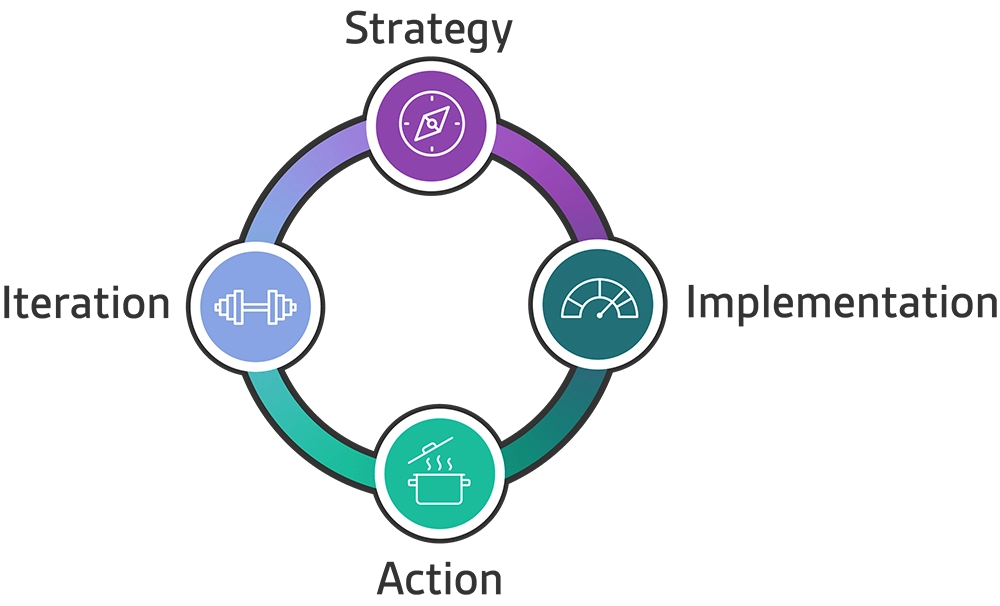
A data analytics road map for success

Laying a solid foundation is key to a succesful, long-term data analytics program. Instead of rushing through critical details and complex issues, we believe that the best data analytics program starts with a:

– personalized, concrete strategy

– clearly defined roadmap

– aggressive implementation plan

Colorful illustration of a circle with the words, strategy, implementation, action, iteration.

The most flexible data analytics solution available to banks and credit unions

PRODUCT STATS

Faster Implementations
0 %
Integrations
0 +
Implementation Fees
$ 0
Integrations
0 +
Total Customers
0 M+

CLIENT STATS

Total Assets
$ 0 B+
Total Customers
0 M+
Total Deposits
$ 0 B+
Total Assets
$ 0 B+
Total Deposits
$ 0 B+
mint green triangle

News and Resources

What Operations Data Can Tell You That Financial Data Cannot

What Operations Data Can Tell You That Financial Data Cannot

At most credit unions and community banks, the financial reports are the reports. The monthly financials, the board package, the performance summary: these are what leadership reviews, discusses, and makes decisions from. They are essential, and they are also incomplete. Financial data is very good at telling you what happened. It is far less good at telling you why it happened, or what is about to happen next. For those answers, you need a different kind of data entirely. Operational data, the information about how your institution actually runs day to day, answers the questions financial data cannot. It captures the activity that eventually becomes a number on a statement. Paying attention to both is what separates an institution that reacts to its results from one that shapes them. Why Financial Reports Only Tell You What Already Happened A financial statement is a record of the past. By the time a result lands in a monthly report, the activity that produced it is weeks or months gone. If loan yield slipped, the financials will confirm it slipped, but only after the quarter closed and only in aggregate. They will not tell you which branches, which products, or which member and customer segments drove the change, and they will not tell you in time to do anything about it while it is happening. This is what financial data is for: it measures outcomes. The problem arises only when an institution treats outcome data as its sole lens, because outcomes are the one thing you can no longer influence by the time you see them. A soft quarter shows up clearly in the financials, but the financials cannot tell you what to do about it, because the causes they summarize are already in the past. What Operational Data Reveals About Why Results Change Operational data captures the activity beneath the financial result. Where the financials show that new account growth was down, operational data shows the branch traffic patterns, the onboarding completion rates, and the staffing levels that explain the decline. Where the financials show a dip in a product line, operational data shows the product penetration trends across branches that reveal where and why interest fell off. This is the difference between knowing a number and understanding it. The financials can show that a result moved, but the explanation, and therefore the fix, lives in the operational data underneath. When the two are connected, a disappointing result stops being a mystery to be debated in a meeting and becomes a problem with a visible cause and an addressable solution. Mobility CU, a Gemineye data lakehouse client, offers a useful example. How much the credit union recovered on car repossessions is the financial report. Which reseller is yielding the highest margin is the operations report. How Operational Signals Warn You Before the Financials Do The most valuable thing operational data offers is time. Because it sits upstream of the financials, it moves first. A decline in onboarding completion shows up in the operational data this month, well before it shows up as reduced product adoption and lower revenue in next quarter’s financials. A shift in branch service patterns is visible immediately, long before it registers as a change in member or customer retention numbers. This early visibility is what turns management from reactive to proactive. An institution watching only its financials finds out about problems after they have already cost money. An institution watching its operational data sees the warning signs while there is still time to respond, which means many problems get solved before they ever reach the financial statement at all. The financials still matter, but they become confirmation of good management rather than the first notice of a problem. Why Both Data Types Belong in the Same View None of this argues for replacing financial data. It argues for pairing it with operational data so that each makes the other more useful. Financial data tells you the result. Operational data tells you the cause and the early warning. Seen together, they let leadership move from asking what happened to asking why, and from reacting to results to shaping them before they land. The obstacle for most institutions is that these two kinds of data live in different systems that were never connected. The financials come from the core and the general ledger. The operational data is scattered across core, digital banking, branch systems, origination, and service platforms. Bringing them into one view, where an operational trend can be seen alongside the financial result it explains, is what makes the full picture possible. Without that connection, leadership is left with half the story and no reliable way to assemble the rest. See the Full Picture With Gemineye Understanding why your results change, and seeing the warning signs early, depends on bringing operational and financial data into one connected view. Gemineye’s Operations solution connects the systems behind your institution and delivers detailed daily reporting on the operational activity, from branch performance and staffing to product penetration and onboarding, that explains what your financials can only report after the fact. See how Gemineye helps credit unions and community banks manage from the full picture rather than half of it.
How to Make the Case for Platform Investment When Your Backlog Speaks for Itself

How to Make the Case for Platform Investment When Your Backlog Speaks for Itself

You know the platform would pay for itself. You live inside the problem every day: the backlog that never clears, the manual work that eats your team’s hours, the requests you cannot get to because you are buried in the ones you can. The difficulty is not knowing that an investment is justified. It is translating what is obvious to you into an argument that (1) wins approval from a CFO who does not live inside the problem and (2) who is weighing your request against every other demand on the budget. But your backlog is not just evidence of a problem. Handled well, it is the strongest argument you have. This is a guide to turning the daily reality of an overloaded data function into a business case that a credit union or community bank leadership team will actually approve. Why a Data Leader Should Lead With Cost, Not Capability The instinct when pitching a platform is to talk about what it does: the features, the dashboards, the technical capabilities. To a CFO, this is the least persuasive framing available. Capabilities sound like expenses. What a CFO responds to is cost, specifically the cost the institution is already paying without a platform, whether or not anyone has named it. Reframe the conversation around what the status quo costs. Your team’s hours spent manually assembling reports carry a real dollar value. Decisions delayed while people wait for data slow the institution down in ways that show up on the bottom line. Opportunities missed because no one could see them in time are revenue the institution never captured. When you present the platform as a way to stop paying these existing costs rather than as a new expense to take on, the entire conversation changes. You are not asking to spend money. You are showing how the institution is already losing it. How to Turn Your Backlog Into Hard Numbers A backlog is persuasive precisely because it can be quantified. Start by making the invisible visible. How many requests does your team receive in a month, and how many can you actually complete? The gap is not a reflection of your team’s effort. It is a measure of unmet demand, and unmet demand is unrealized value sitting on the table. Then attach time to the recurring work, and let it accumulate. A single monthly report that takes a skilled analyst a full day to assemble by hand is twelve days a year on its own, which may sound modest until you multiply it across every recurring report, every reconciliation, and every ad hoc pull the team rebuilds from scratch. And let’s not forget about the manual recurring activities on the executive team’s side, outside of the data team. From executive level and all the way down, teams get bogged down with incessant tasks that eat away at productivity: Executives manipulating numbers for board reports, every single branch manager adjusting numbers for branch performance. Summed across the year, the figure becomes striking. A CFO who sees that a meaningful share of a business team’s capacity is consumed by work a platform would automate understands the investment immediately, because now it is expressed in the currency they think in: time, money, and opportunity. Look to P1FCU for an example of streamlining branch operations in a time of expansion. Using the Gemineye Data Lakehouse, they were able to develop an innovative report that visualized how much time tellers at each branch were spending on operational activities. Why the Strongest Argument Is About Growth, Not Just Efficiency Efficiency gets attention, but growth wins budgets. The most compelling business case connects the platform not only to hours saved but to value created: the members or customers retained because the team could finally see who was at risk of leaving, the lending opportunities identified earlier, the products matched to the right people. Filene’s analytics readiness research makes a related and useful point for this argument, finding that the single most critical driver of value from analytics is a low-cost investment in building a data-driven culture, not the largest technology purchase. That is a helpful framing, because it lets you position the platform as the enabler of that culture rather than as an expensive end in itself. When you tie the investment to the institution’s actual strategic goals, whether that is growing loans, deepening relationships, or competing with larger players, the platform stops being a data-team expense and becomes a lever for the outcomes leadership already cares about. That is the framing that moves a request from the maybe pile to the approved one. How to Navigate the Objections a CFO Will Raise Your CFO may have concerns that sound like objections, but are actually just questions. The Gemineye team often see these questions arise: Is the solution compatible with all our existing sources? Is the partner experienced with our specific sources and business concerns? Can the implementation plan adapt to all of our other strategic initiatives? Is the solution sustainable and can it support future data maturity stages? You can mitigate concerns by ensuring there is a vehicle for open and honest communication and time set aside to inform your CFO. Helping them stay informed encourages confidence, which motivates a positive decision. Another common objection from the financial team can include some version of “can we not just keep doing what we are doing?” The answer is the cost argument you have already built. Continuing as-is is not free. It carries the ongoing, compounding cost of unmet demand and wasted capacity, and that cost grows every year the institution adds systems and members or customers. Standing still is itself an expensive choice, just an unnamed one. Build the Case With a Platform Made for Your Institution The strongest business case is easiest to make when the platform genuinely fits how a credit union or community bank works. Gemineye’s Data Analytics platform is built specifically for financial institutions, integrates with the systems you already run, and reduces manual ...

What the Most Data-Mature Credit Unions and Community Banks Do Differently

What the Most Data-Mature Credit Unions and Community Banks Do Differently

Walk into two credit unions of similar size and asset base, and you can often tell within a few minutes which one is further along with its data. It is not about who has the biggest budget or the largest team. It is about a set of habits and choices that separate the institutions treating data as a genuine asset from the ones still treating it as a monthly chore. These differences accumulate quietly, and they are why some institutions steadily outperform peers who look identical on paper. Data maturity is not a product you buy or a milestone you reach once. It is a way of operating, and the habits behind it are learnable at any size. Here is what the most data-mature institutions consistently do differently. Why Data-Mature Financial Institutions Invest in Infrastructure, Not Reports Less mature institutions think about data in terms of outputs: the monthly board report, the quarterly numbers, the dashboard someone requested. Mature institutions think about data in terms of foundation. They invest in the underlying infrastructure that connects their systems and keeps their data clean and consistent, because they understand that every report, every insight, and every decision downstream depends on that foundation being solid. This shift in thinking changes where the effort goes. Instead of repeatedly rebuilding the same reports by hand, mature institutions build the plumbing once and let reports flow from it. Their teams spend less time assembling data and more time interpreting it, which is the work that actually moves the business. How a Data-Driven Culture Replaces Decisions Made on Instinct The clearest marker of data maturity is cultural. In mature institutions, when a strategic question comes up, the reflex is to ask what the data says, not to default to the most senior person’s intuition. This does not mean instinct has no place. It means instinct is informed by evidence rather than substituting for it. Wipfli notes that data can guide decisions as concrete as where demand for financial services is highest, so institutions place the right services in the right locations. That is the kind of question mature institutions answer with evidence rather than guesswork. Building this culture takes more than tools. It requires leaders who ask for data, trust it when they get it, and are willing to change their minds when the evidence points somewhere unexpected. When staff see leadership decide this way, the behavior spreads. How Data-Mature Institutions Extend Access Beyond the Executive Suite In less mature institutions, data access is concentrated. A small number of people can pull reports, and everyone else waits in line. In mature institutions, access is distributed. A branch manager can see their own performance data. A lending officer can check portfolio metrics. A marketer can pull a member or customer segment. The data team enables this access rather than gatekeeping it. This distribution is what turns data from a specialized function into an organizational capability. When everyone who makes decisions has access to the data relevant to those decisions, the quality of decisions rises across the whole institution, not just at the top. It also frees the data team from being a report factory, so their expertise goes toward the harder problems only they can solve. Why Consistent Data Definitions Separate Trusted Numbers From Disputed Ones One quiet but powerful difference is definitional discipline. In mature institutions, an active member or customer means the same thing in every report, every department, and every conversation. Definitions are agreed upon, documented, and maintained. This sounds mundane, but it is the difference between a leadership team that trusts its numbers and one that spends meetings arguing about whose figures are right. Less mature institutions often have the same data defined differently across departments, which quietly undermines every report built on it. Mature institutions treat consistent definitions as a foundational asset, because trust in data is impossible without it, and data cannot drive decisions until people stop second-guessing the inputs. How Data-Mature Financial Institutions Plan for the Long Term, Not the Next Report Perhaps the deepest difference is time horizon. Less mature institutions operate reactively, solving each data request as it arrives and never getting ahead of the work. Mature institutions operate with a roadmap. They know which capabilities they are building toward, they sequence their work so each project makes the next one easier, and they invest in foundations that pay off over years rather than chasing the next report. This long-term orientation is what allows data maturity to build on itself. Each investment strengthens the next, and the distance between a mature institution and a reactive one widens every year. The institutions that start operating this way, even from a modest starting point, are the ones that eventually lead their peers. Move Your Financial Institution Up the Maturity Curve Every one of these habits depends on a data foundation that makes them possible: connected systems, consistent definitions, and broad, governed access. Gemineye’s Data Analytics platform gives credit unions and community banks that foundation, so the behaviors that define data maturity become achievable regardless of team size. See how Gemineye helps institutions operate like the most data-mature players in their field.

Showing Slide 1 of 4

News and Resources

Ann Ditlow and bento box
Ann Ditlow: Data Analyst at 4Front CU

Welcome to our very first edition of “A Day in the Life of a Data Analyst,” featuring the equally talented and down-to-earth Ann Ditlow, Data Analyst at 4Front CU. Ann ...

gemineye quorum anniversary
Gemineye and Quorum Federal Credit Union Celebrate Five-year Anniversary

The team at Gemineye is excited to announce their five-year anniversary with Quorum Federal Credit Union, a $1.1B organization headquartered in Purchase, NY. Quorum is an entirely-online credit union with ...

gemineye logo and databricks logo with confetti
Gemineye Announces Partnership with Databricks

  Gemineye (formerly The Knowlton Group) has partnered with Databricks, the world’s leading data and AI company. Gemineye’s innovative data analytics architecture, called the Gemineye Data Lakehouse, is run entirely ...

Showing Slide 1 of 4
mint green triangle

Ready to finally have control over your data analytics experience?

We offer complimentary consultations – never pushy, always honest.